









Many Canadian townhouses have an association that handles monthly upkeep and commonly used areas like sidewalks, offering residents an opportunity to enjoy the convenience of condo renting and the control of home ownership in one. However, sharing characteristics with both condo units and freestanding homes has caused some confusion about which type of insurance a prospective owner may need.
Should townhouse owners get a condo insurance policy or a home insurance policy to cover their townhouse? Keep reading to learn more about different types of townhouses, the difference between condo and home insurance, and what affects the average cost of townhouse insurance in Canada.
What Insurance Does a Townhouse Owner Need in Canada?
- Most townhouses are considered condominiums in Canada, so you’ll likely need condo insurance instead of a home insurance policy. Talk to your real estate agent to make sure what type of policy is appropriate for your property.
- If your townhouse shares walls with other units, ask your real estate agent how many shared walls there are and if there are fire code-compliant firewalls with sufficient fire resistance, as these will impact your townhouse insurance rates.
- If you haven’t purchased the townhouse yet, check the listing for keywords like “shared” or “communal” or any listed condominium fees. These strongly indicate that the applicable type of policy to get is condo insurance, not home insurance.
Condo vs Home Insurance: What’s the Actual Difference?
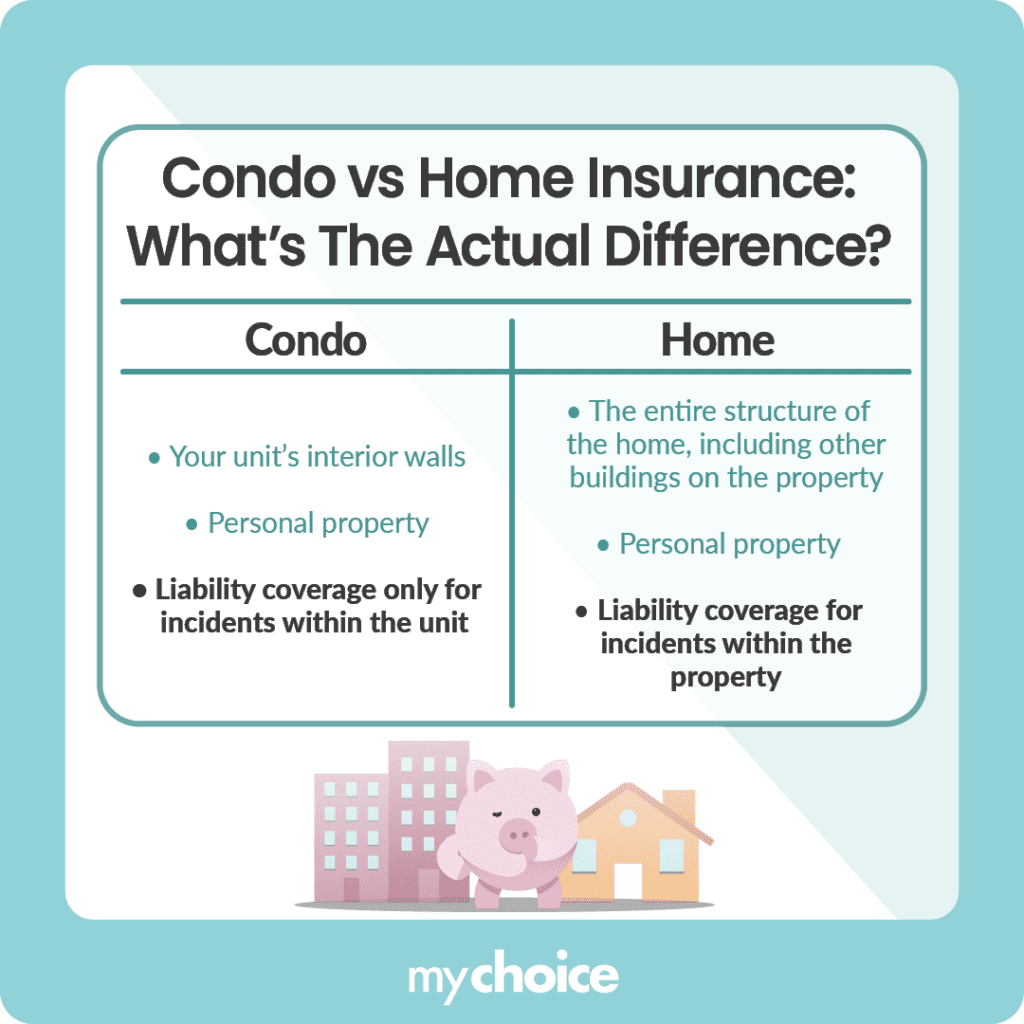
It’s not so simple to separate condo insurance from corporation insurance into “what’s inside and outside your condo,” because condo insurance works with the corporation policy. A typical homeowners insurance policy insures your house, personal property, additional living expenses and liability, as specified in the policy terms.
| For a condo or strata townhouse, obtain | Reason |
|---|---|
| Declaration or strata plan and unit boundaries | Shows which parts of the building, roof, walls, parking or yard belong to the unit and which are common property |
| Standard-unit or reference-unit definition | Helps define where corporation- insured property ends and owner improvements begin |
| Current corporation insurance certificate and wording summary | Shows corporation-insured property, coverage limits, major exclusions and the corporation deductible |
| Insurance and deductible bylaws | May extend the circumstances in which an owner can be charged the corporation’s insurance deductible |
| Status, estoppel or disclosure documents | May indicate outstanding claims, insurance issues, fees, reserve funds and proposed changes |
| Lender requirements | A mortgage can require insurance even where provincial law does not impose the same owner coverage |
Read More: See How Loss Assessment Coverage Works for Condos
Townhouse Coverage Checklist
- Which buildings, structures, fixtures and parts of the unit do I need to insure?
- Contents: what’s the total value if they had to be replaced? Are there specific coverage limitations for certain items?
- Improvements and betterments: how do they compare with the reference or standard unit?
- Additional living expenses: what’s the limit? Are there specific perils that must be insured before coverage is available?
- Personal liability: this can apply to occurrences outside your unit. Who is insured?
- Loss assessment, unit contingency or corporation-deductible coverage: what’s covered? What are the limits and deductibles?
- Optional coverages such as overland water, sewer backup, service lines and earthquake coverage.
- If there’s a chance you might rent out your unit or use it for a business, tell the insurer. Do not rely on a regular owner-occupied policy.
- In Quebec, third-party liability insurance is mandatory for divided co-owners, and the statutory minimums depend on the number of units in the building.
Read More: Compare Broad and Comprehensive Home Insurance
How to Compare Townhouse Insurance Quotes
Before comparing rates, make sure all the quotes have the same liability and coverage limits, water-damage coverage, loss assessment coverage, additional living expenses and deductibles. Avoid comparing your costs with national averages.
Read More: Learn How Replacement Cost Differs From Actual Cash Value