
The cost of owning a car is the value it loses plus interest, fuel, insurance, maintenance, registration, parking and other operating expenses. Your loan payment is not the same as ownership cost because part of each payment builds equity in the vehicle. You need both calculations before deciding what you can afford.
For this guide, our team checked Statistics Canada’s fuel price data and vehicle-use data, Natural Resources Canada’s fuel-consumption guide and CAA’s driving-cost calculator.
Keep reading for a worked first-year example, the monthly cash-flow version and a template you can replace with your own vehicle, loan and driving assumptions.
What Costs Belong in a Car Budget?
| Cost | How to calculate it |
|---|---|
| Depreciation | Purchase price minus expected resale value after the period |
| Financing | Interest and lender fees, not the principal repaid |
| Fuel or electricity | Annual distance multiplied by energy use and price |
| Insurance | Your annual quote for the vehicle, drivers, address and coverage |
| Maintenance and tires | Scheduled service, tire costs and a repair reserve |
| Taxes and registration | Sales tax, registration, plate and province-specific renewal costs |
| Parking, tolls and permits | Your home, work and routine-trip costs |
Read More: See the Hidden Costs of Owning an Electric Car
Worked Example: A $60,000 New Vehicle
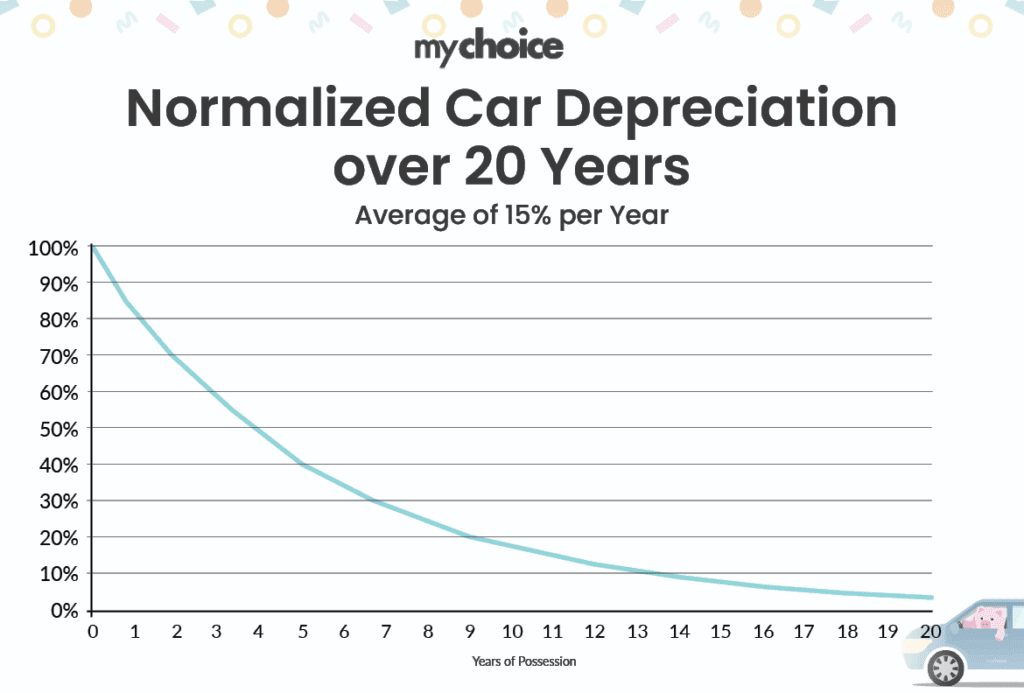
This is an illustration, not a Canadian average. Assume a $60,000 purchase price, $6,000 down payment, a $54,000 five-year loan at 6.5%, 15,000 kilometres a year, fuel use of 8.5 L/100 km, fuel at $1.54/L, $1,500 for maintenance and tires, and a $48,000 resale value after one year.
| First-year economic cost | Calculation | Amount |
|---|---|---|
| Depreciation | $60,000 minus $48,000 | $12,000 |
| Loan interest | First 12 months of the stated amortization | $3,232 |
| Fuel | 15,000 ÷ 100 × 8.5 × $1.54 | $1,964 |
| Insurance | Standardized Ontario MyChoice profile | $2,345 |
| Maintenance and tires | Scenario reserve | $1,500 |
| Total | Before tax, registration, parking, tolls and unexpected repairs | $21,041 |
The economic cost is about $1,753 a month. That number includes depreciation but excludes principal repayment, sales tax and the down payment because those amounts convert cash into vehicle equity rather than disappearing immediately as an expense.
What Is the Monthly Cash Flow?
The loan payment in this example is about $1,057 a month. Add about $164 for fuel, $195 for insurance and $125 for the maintenance reserve. That produces a monthly cash requirement of about $1,541 after the down payment, before parking, tolls, registration and unexpected repairs.
Cash flow and economic cost answer different questions. Cash flow tells you whether the bills fit your monthly income. Economic cost shows how much wealth the vehicle consumes after accounting for lost value.
Read More: Compare Leasing and Financing a Car in Canada
How to Personalize the Calculation
Replace the purchase price and expected resale value with prices for the exact model. Use the loan disclosure for the payment, APR, term and total borrowing cost. Look up the vehicle’s fuel-consumption rating, then multiply it by your expected kilometres and a fuel price that reflects your area.
Get an insurance quote before signing the purchase agreement. Add winter tires, parking, tolls, registration and a maintenance reserve based on the warranty and service schedule. Run a low, expected and high scenario instead of trusting one precise total.
How Do New, Used and Electric Vehicles Change the Total?
A used vehicle can reduce depreciation and borrowing, but it may need a larger repair reserve. An electric vehicle removes gasoline but adds electricity use and may have different purchase, tire, repair and insurance costs. Compare vehicles over the same ownership period and expected resale date.
Read More: Compare Buying a New and Used Car