









“One-way insurance” isn’t an official type of car insurance. It usually refers to a policy with only the mandatory coverages. Damage to your own vehicle from a collision, theft or severe weather may not be covered.
One-way insurance can be beneficial to drivers who are on a tight budget, as it offers the basic coverage needed to drive legally.
Read on to learn more about what one-way car insurance covers, how it differs from other forms of auto insurance coverage and whether this kind of policy is right for you.
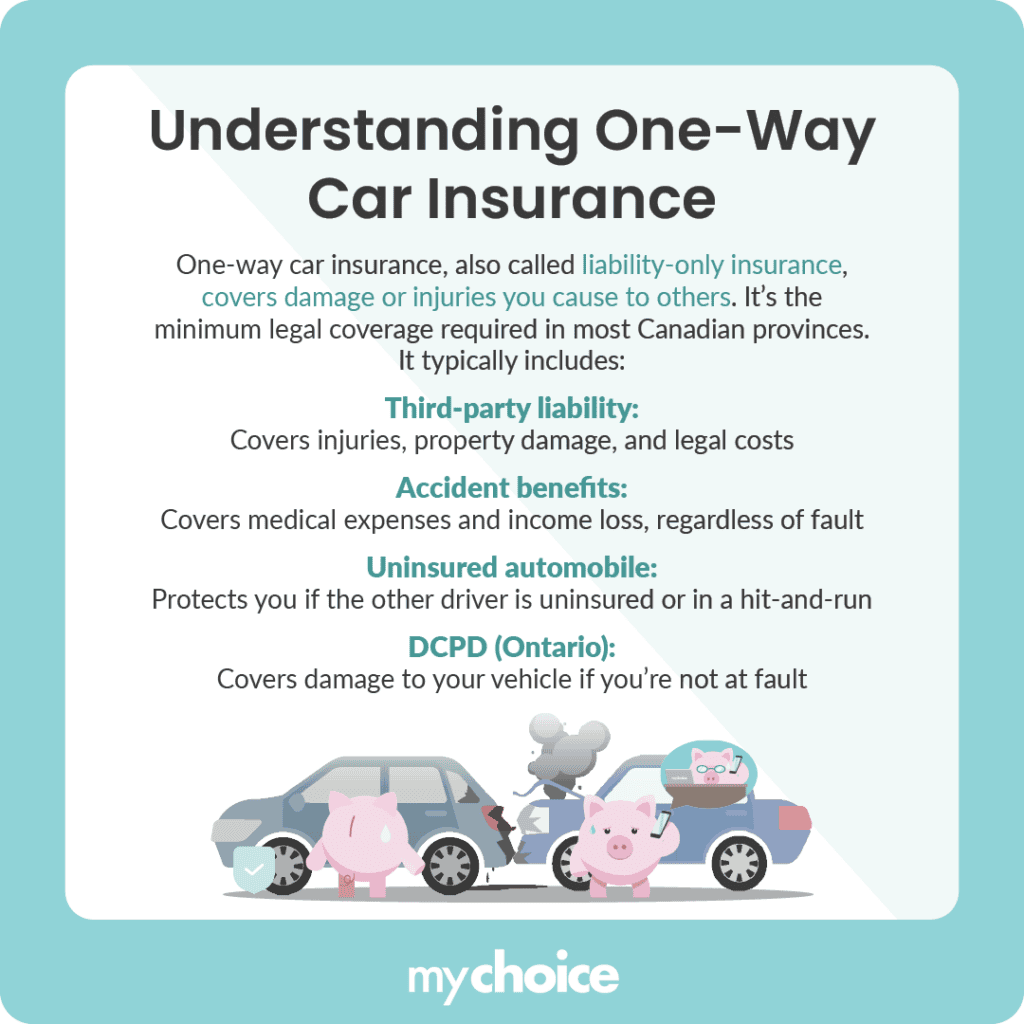
Understanding One-Way Car Insurance
One-way insurance usually refers to a policy that keeps the mandatory coverages but leaves out optional Collision and Comprehensive coverage.
One-way insurance in Ontario generally includes the following coverage:
- Third-party liability coverage: This covers the cost of damaging another person’s property or injuring another person in an accident. Third-party liability coverage may cover eligible injury, property damage and legal costs, subject to the policy limit.
- Accident benefits coverage: This provides eligible benefits if you’re injured in an accident, regardless of who caused it. The benefits available depend on your policy.
- Uninsured automobile coverage: This may protect you if you’re injured or killed by an uninsured or unidentified driver. It may also cover damage to your vehicle caused by an identified uninsured driver.
- Direct Compensation Property Damage coverage: DCPD may cover damage to your vehicle and its contents if you’re not at fault and the conditions for coverage are met. Ontario drivers can choose not to claim this coverage.
One-Way vs. Two-Way Car Insurance
Unlike one-way insurance, two-way insurance is more comprehensive, as it covers everything that one-way insurance does and adds protection for the policyholder’s car.
Two-way insurance may include:
Collision coverage: This covers the cost of repairing or replacing your vehicle after it hits another vehicle or object or rolls over. If the repair cost is higher than the car’s value, your insurer may declare it a total loss.
Comprehensive coverage: This covers certain losses outside of a collision, including theft, vandalism, fire, hail, rising water and collisions with animals.
Other optional coverages may include:
- Accident forgiveness coverage: Accident forgiveness may protect your premium following your first qualifying at-fault accident, subject to its terms.
- Loss-of-use coverage: This may cover the reasonable cost of renting a vehicle or taking other transportation if your car is damaged by an insured peril and needs repairs.
Who Can Benefit From One-Way Car Insurance?
One-way car insurance isn’t for everyone, but it can be an option for the following people:
Drivers on a Budget
A lower premium helps only if the driver can afford repair, replacement and transportation costs that insurance may not cover.
Drivers With Older Cars
Vehicle age alone is not enough. Compare the car’s estimated value after the deductible with the premium saved and the amount needed for a replacement.
Drivers Who Rarely Use Their Cars
Low use may reduce collision risk, but a parked vehicle can still face theft, fire, severe weather and vandalism. Ask whether reducing one coverage leaves the protection you still need.
Drivers Who Are Willing to Cover Repair Costs
Paying for repairs yourself works only when you have enough savings to cover repairs or replacement and no lender or lessor requires physical-damage coverage.
Drivers Who Can Accept the Risks
People have different degrees of risk tolerance, or the ability and willingness to accept an outcome and its consequences. With one-way insurance, you’re weighing your chances of being involved in an accident and your ability to pay for the damage against the cost of a more expensive policy.
Financial and Legal Implications of One-Way Car Insurance
There are risks involved with getting only one-way insurance. It may not cover damage to your vehicle after an at-fault accident. Without Comprehensive coverage, theft, vandalism and severe-weather damage may not be covered either.
You may also have trouble financing a vehicle without Collision or Comprehensive coverage. Most lenders require financed vehicles to have these two types of coverage.
Can I Get Sued if I Only Have One-Way Insurance?
You can get sued for a car accident whether you have one-way or two-way insurance. A lawsuit may be filed when:
- The parties cannot agree on who was at fault.
- The parties cannot agree on the settlement amount.
- A legal deadline is approaching.
- The value of the claim may exceed the available liability coverage.
If a covered liability claim exceeds your policy limit, you may be personally responsible for the remaining amount.
In any case, make sure to report a car accident to your insurer as soon as possible.
How to Manage the Risks Associated With One-Way Car Insurance
If you don’t want to purchase two-way insurance but are worried about the risks, the following tips may help:
- Set up an emergency fund: Make sure you have enough money to cover repairs, replacement and another mode of transportation while your vehicle is out of commission.
- Drive less: The less you drive, the lower your risk of being involved in an accident.
- Drive safely: Follow traffic rules, maintain a safe distance between you and the vehicle ahead of you and make sure you’re visible to other drivers.
- Install a theft-deterrent system: To reduce the risk of theft, consider anti-theft devices such as wheel locks, tracking systems and Faraday bags.
- Consider usage-based insurance: Also known as pay-as-you-go insurance, this uses telematics to record information about your driving. Depending on the program, your driving habits may help you qualify for savings.