









You can have more than one life insurance policy, but the number of policies does not determine whether you have the right amount or whether each application will be approved.
Layering policies can make sense in some circumstances. For example, you may be able to align different end dates with specific needs and get more targeted coverage. However, a single policy may be more convenient. When applying for a new life-insurance policy, insurers will consider the total amount of coverage you already have. It’s also a good idea to compare costs before replacing existing coverage that may be working for you.
This guide draws on the federal life-insurance guide, FSRA’s life-policy guide, CISRO’s Life Insurance Replacement Declaration guidance and CRA’s guide to capital property at death.
Is It Worth Having Multiple Life Insurance Policies?
Insurers can issue multiple policies, but the starting point should be determining the total financial shortfall.
Multiple policies do make sense if different aspects of the coverage require different end dates, if you get a new dependant after purchasing the original policy, or when individual coverage supplements a workplace plan. Multiple policies aren’t necessary if you just want to provide for more than one person, as one policy allows you to nominate multiple beneficiaries and allocate shares.
Life insurers will also want to know if you have other life insurance in place, as well as applications currently under consideration. Each insurer determines, under its rules, whether the total amount of your life insurance is financially justified.
Read More: Read About Canada’s Life Insurance Coverage Gap
Why Consider Having More Than One Life Insurance Policy?
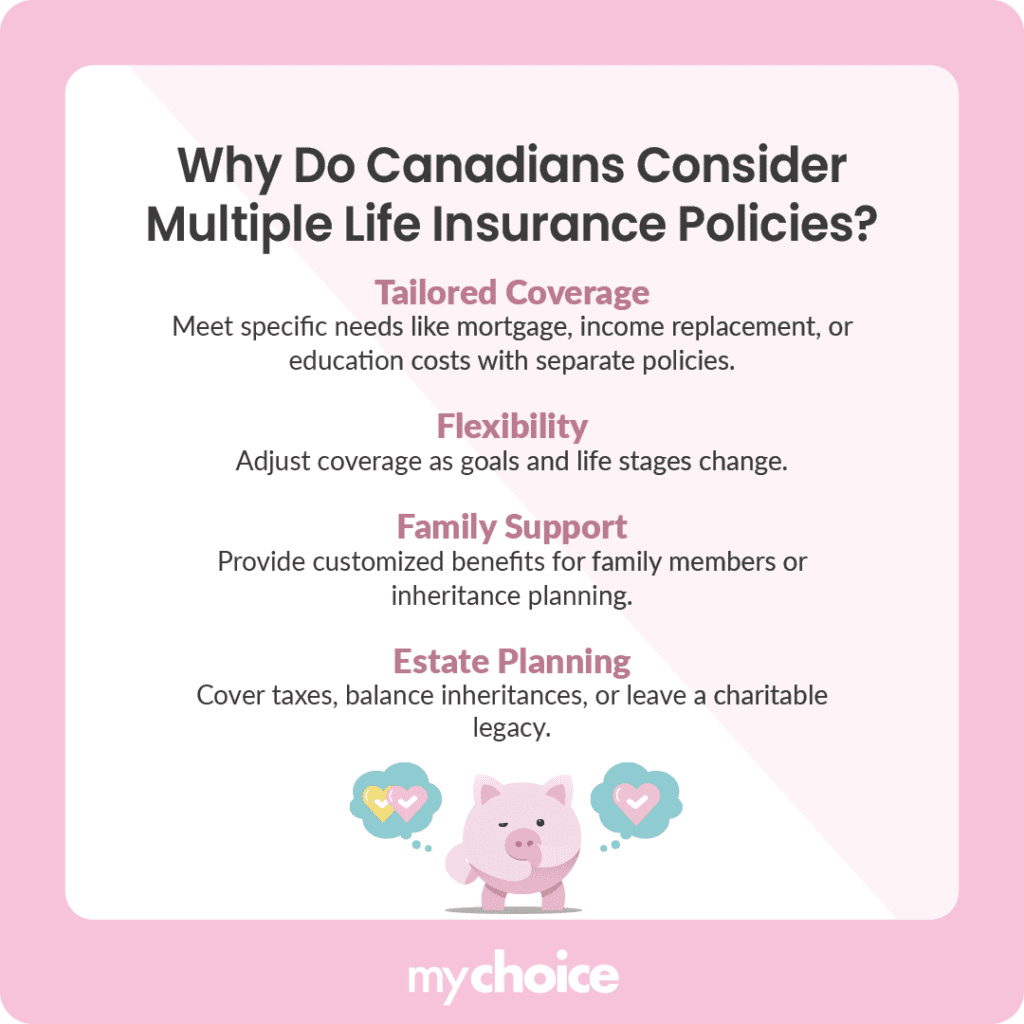
Tailored Coverage For Different Needs
Term policies can be structured in a ladder formation (term ladder) to reflect different needs and their timeframes. For example, one part of the ladder could expire upon projected mortgage payoff, while another could expire when a younger child is expected to become independent. Include permanent coverage only when there is a supported lifelong need and ability to pay. Don’t automatically include a permanent life insurance policy to help with retirement savings.
Read More: Estimate Your Total Life Insurance Need
Flexibility For Evolving Goals
A second life insurance policy can provide coverage that extends beyond the term of the original policy. Changes in your life, like the birth of a child, a later mortgage or increased business obligations, could lead to a desire to increase your life insurance.
If you receive life insurance through work, a personally owned policy remains separate because the job-based plan can end when you leave your job.
Beneficiaries And Claims
Percentage allocation, contingent beneficiaries, provisions for minor beneficiaries, and whether the beneficiaries are revocable or irrevocable are all important to consider when allocating proceeds to beneficiaries.
Different policies can have the same or different beneficiaries. You don’t need different policies to divide proceeds among different beneficiaries.
Each valid and in-force insurance policy has its own claims process. Beneficiaries may need to make a separate claim to each insurer.
Challenges And Considerations For Multiple Life Insurance Policies
| Issue | Why it matters | Control |
|---|---|---|
| Premium and policy fees | Multiple smaller policies aren’t necessarily less expensive than one large policy. | Compare quotes for both structures for the same amount of time. |
| Renewal dates | Premiums on renewable term policies may go up significantly on different dates for different layers. | Record expiry dates, renewal dates, exchange dates and conversion dates, where applicable. |
| Underwriting | Evidence of medical or financial standing may be required, which is an important consideration if taking out a new policy. | Do not cancel current policy until new policy is issued and reviewed. |
| Disclosure | Insurers will ask about other insurance you have or are applying for. | Answer questions consistently in each application. Keep copies of all applications. |
| Beneficiaries | Stale or conflicting beneficiary designations can derail the plan. | Review all policies when life changes occur or laws change, including beneficiaries. |
| Claims | Multiple policies could result in your family having to find and make a claim against each individual policy. | Keep one policy register. Inform beneficiaries where it is kept. |
Estate And Tax Terminology
In Canada, there is no inheritance or estate tax in the general sense. However, most types of capital property are deemed disposed of at the owner’s death, which can trigger income tax on the deceased’s final return unless the assets are exempt or eligible for a rollover that defers the tax.
Provinces or territories impose probate or estate-administration fees. Proceeds payable to a named beneficiary are treated differently from proceeds payable to the deceased’s estate, which can form part of the estate.
Consult your legal and tax advisors regarding funding for taxes, trusts, corporate ownership and other items that might be considered when planning for estate equalization.
Alternatives To Multiple Life Insurance Policies
Ask whether your existing policy can be increased, whether new medical or financial evidence is required, and how previous policy provisions change when you increase coverage.
Split the death benefit among several people using percentage allocations.
Add a term rider and learn its cost, expiration, conversion options and whether you or another person will be insured. Use it only if those terms fit the need.
Add a child term rider, which pays out upon a child’s death, not for the parent’s dependency coverage.
Convert your term coverage within the allowable options and timeframes designated in the contract. You can avoid medical underwriting on the converted portion. However, this may be very expensive.
Reduce your coverage, if allowable in the policy, when your financial shortfall has declined. Find out if you can increase coverage later.
Replacing Or Cancelling An Existing Policy
If the policyholder has an existing policy that will be replaced, do not cancel the policy until the new policy has been issued, delivered, reviewed and is in force.
Compare suicide and contestability periods, conversion features, guarantees, exclusions, cash values, surrender charges and the premium schedule.
If a policy is being replaced, required replacement disclosure must be completed. CISRO says all provinces except Quebec require its Life Insurance Replacement Declaration. Quebec and British Columbia have separate provincial guidance for replacement disclosure.
Read More: Review the Risks of Cancelling an Existing Life Insurance Policy